You scan a QR code.
Enter ₹5,000.
Type your UPI PIN.
Then something goes wrong.
Your UPI app says:
“Transaction Failed.”
But when you check your bank account, ₹5,000 has already been debited.
Now the real panic begins.
“If the payment failed, where did my money go?”
“Will I get it back?”
“Should I pay the merchant again?”
“How long does a UPI refund take?”
First, don’t assume that your money is permanently lost.
NPCI’s UPI Help guidance says that in the case of a wrong debit on a pending or failed transaction, the money is credited back to the account, and users can raise the issue through UPI Help.
But there is something many UPI users don’t know:
The official refund timeline can be different depending on what kind of UPI transaction failed.
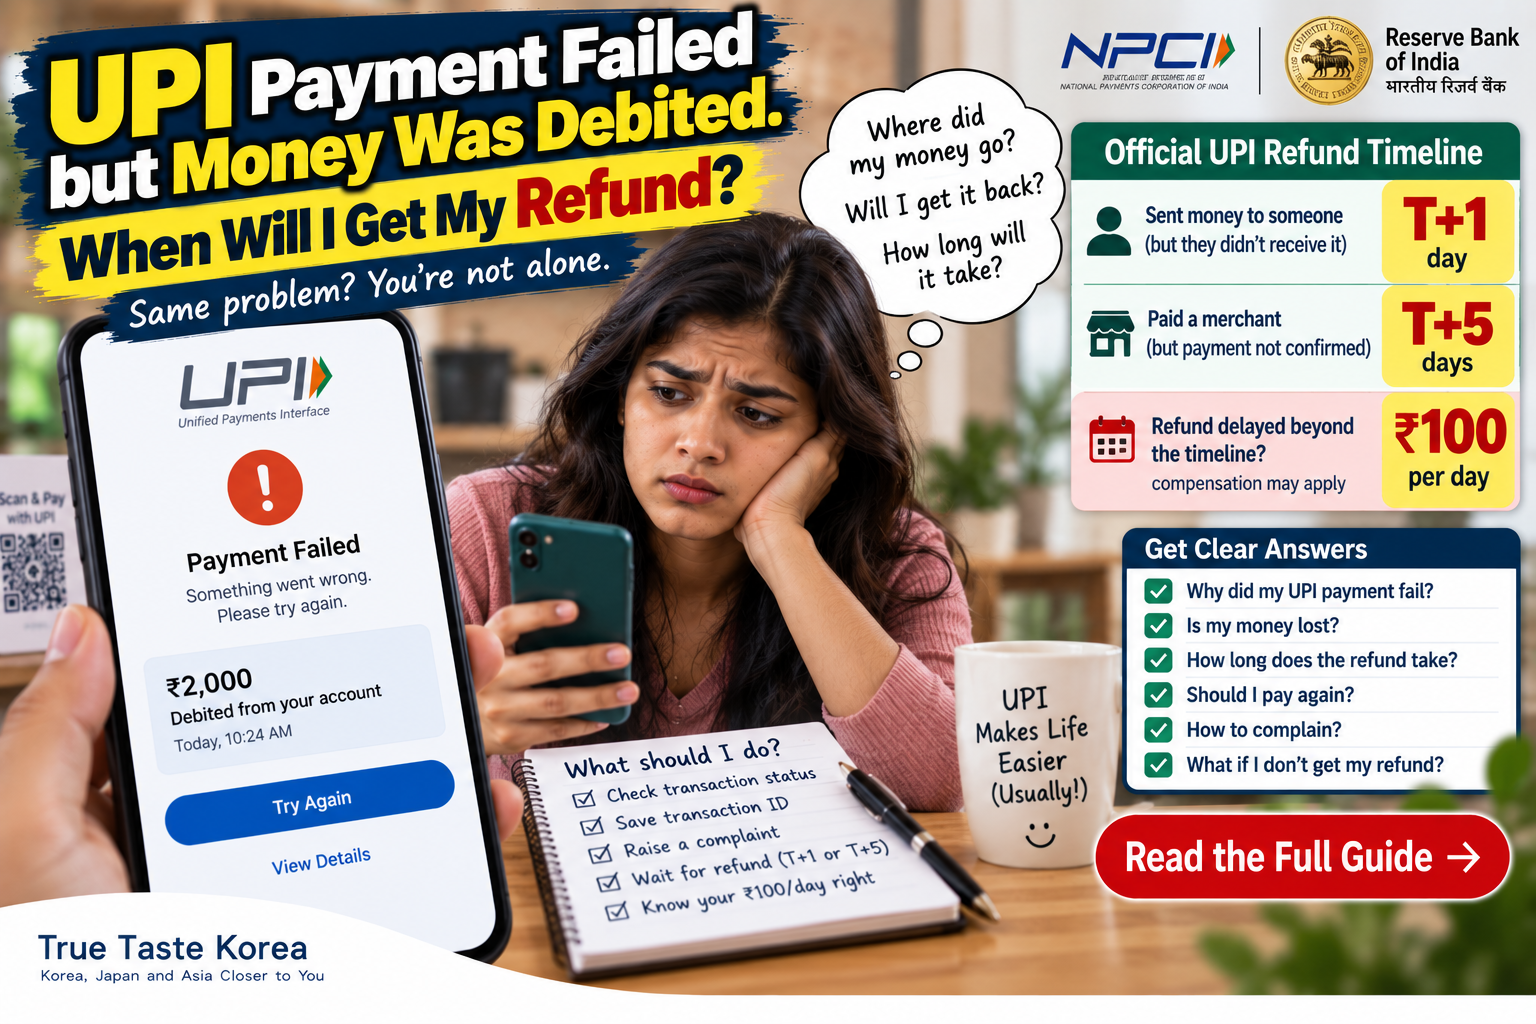
For some failed transfers, the RBI framework specifies T+1 day.
For certain failed merchant payments, it specifies T+5 days.
And if the reversal takes longer than the applicable timeline, the RBI framework provides for compensation of:
₹100 per day of delay.
Here’s how it works.
First: Is My Money Lost If UPI Failed but My Account Was Debited?
Usually, a failed transaction and a debit from your bank account do not automatically mean the money has disappeared permanently.
A UPI transaction involves multiple systems.
Your bank account may have been debited, but something can go wrong before the beneficiary receives the money or before the merchant receives confirmation.
That creates the frightening situation where:
Your bank: Money debited.
UPI app: Transaction failed.
Receiver: No money received.
NPCI’s UPI Help documentation specifically addresses wrong debits on pending or failed transactions and says the money will be credited back to the user’s account.
The important question then becomes:
When?
And that’s where you need to know whether this was a fund transfer or a merchant payment.
UPI Refund: T+1 or T+5?
This is probably the most important part of this article.
People often hear conflicting advice online:
“Wait one day.”
or:
“UPI refunds can take five days.”
Both statements can make sense because RBI’s framework distinguishes between different failed UPI transactions.
Case 1: You Sent Money to Someone, but They Didn’t Receive It
Suppose you send:
₹10,000
to a friend or family member.
Your account is debited.
But the beneficiary’s account is not credited.
Under the RBI framework for a failed UPI transfer of funds, if the beneficiary cannot be credited, the transaction should be auto-reversed by the beneficiary bank no later than:
T+1 day.
If the reversal is delayed beyond T+1, the prescribed compensation is:
₹100 per day of delay.
So the basic rule is:
Account debited
↓
Beneficiary not credited
↓
Auto-reversal: T+1
↓
Beyond T+1: ₹100/day compensation
Case 2: You Paid a Merchant, but the Merchant Didn’t Receive Confirmation
Now imagine a different situation.
You are at a restaurant.
Your bill is ₹2,000.
You scan the restaurant’s UPI QR code.
₹2,000 leaves your bank account.
But the restaurant’s payment system doesn’t receive confirmation.
The cashier says:
“Payment failed. Please pay again.”
This falls under a different part of the RBI framework.
For a UPI payment where the account is debited but transaction confirmation is not received at the merchant location, RBI specifies:
Auto-reversal within T+5 days.
If the reversal is delayed beyond T+5 days, the compensation specified is:
₹100 per day of delay.
So:
Account debited
↓
Merchant confirmation not received
↓
Auto-reversal: T+5
↓
Beyond T+5: ₹100/day compensation
That’s why you should not assume that every failed UPI transaction has exactly the same refund deadline.
What Does “T” Mean?
In RBI’s framework:
T is the calendar date of the transaction.
So if the applicable rule is T+1, it means the timeline is calculated from the transaction date according to the framework.
This is different from vaguely being told:
“Wait a few working days.”
The RBI framework establishes specific outer limits for the categories of failed transactions it covers.
Can I Really Get ₹100 Per Day If My UPI Refund Is Late?
Yes—under the circumstances covered by RBI’s failed-transaction framework.
For UPI:
Failed fund transfer
Account debited but beneficiary not credited:
Auto-reversal: T+1
Delay beyond T+1: ₹100 per day.
Failed merchant payment
Account debited but transaction confirmation not received at merchant:
Auto-reversal: T+5
Delay beyond T+5: ₹100 per day.
And there’s another important point.
RBI’s circular states that the compensation should be credited to the customer’s account suo moto—in other words, without waiting for the customer to lodge a complaint or claim.
That’s a useful consumer right to know.
Does ₹100 Per Day Mean I Get My Money Back Plus ₹100?
If your situation qualifies and the reversal is delayed beyond the applicable RBI timeline, the compensation is separate from reversing the failed transaction amount.
For example, the underlying issue might involve ₹5,000 being wrongly debited.
The first objective is getting the ₹5,000 reversed.
The ₹100/day provision addresses delay beyond the applicable outer limit.
However, don’t assume every UPI dispute automatically qualifies.
The precise transaction status and failure category matter.
My UPI App Says “Pending,” Not “Failed.” What Should I Do?
This is another common source of confusion.
Pending and Failed are not necessarily the same thing.
A pending transaction means the system may not yet have determined the final status.
NPCI’s UPI Help guidance says users can check the current status of a transaction and raise complaints on eligible debit transactions. It also notes that the refresh function can retrieve the present status of a pending transaction.
So if you see:
Pending
don’t automatically treat it as a confirmed failure.
Check the transaction status again before taking another action.
Should I Pay the Merchant Again?
This is where you need to be careful.
Imagine:
Restaurant bill: ₹1,500
You pay using UPI.
Your bank account is debited.
The restaurant says:
“We haven’t received the payment.”
The worst thing you can do is panic and lose track of both transactions.
Before paying again, check:
Your UPI transaction status
Your bank-account debit
The UPI transaction/reference ID
Whether the merchant can verify the payment again
If you do need to make another payment because the first transaction genuinely failed, keep evidence of both payments.
Why?
Because the first ₹1,500 may later be automatically reversed.
You need to be able to distinguish:
First failed transaction
from
Second successful transaction.
What Should I Save After a Failed UPI Transaction?
Do not rely on memory.
Save the details immediately.
Keep:
Transaction date and time
Amount
UPI transaction ID/reference number
Recipient or merchant details
Screenshot of transaction status
Screenshot or record showing the bank debit
Any complaint/reference number
If you later need to escalate the matter, these details make it much easier to identify the transaction.
Should I Raise a Complaint Immediately?
You don’t necessarily have to sit and do nothing.
NPCI’s UPI Help guidance says a complaint can be raised on supported debit transactions after five minutes from the transaction.
UPI Help supports complaints for issues including money not being credited to the beneficiary and merchant transactions.
If you use BHIM, NPCI also states that declined transactions can be reported from the transaction history through the Report Issue option.
Other UPI apps may present their support options differently.
The important point is:
Start with the transaction itself.
Don’t search random phone numbers online and hand over your banking information to someone claiming to be “UPI customer care.”
Who Should I Contact: My UPI App or My Bank?
Start with the complaint/support process available for the transaction in your UPI app.
Keep the complaint number.
If the problem remains unresolved, you may also need to contact the bank linked to the debited account.
The key is to provide the exact transaction information rather than simply saying:
“My UPI money is missing.”
Give them:
Amount
Date/time
Transaction/reference ID
Status shown
and the fact that:
Account was debited but the beneficiary/merchant did not receive the payment.
That description matters because it identifies the type of failed transaction.
What If My UPI App and Bank Show Different Statuses?
This can happen.
For example:
Bank: ₹4,000 debited.
UPI app: Pending.
Merchant: Payment not received.
Don’t rely on just one screen.
Check the transaction again in the UPI app and keep the bank debit record.
NPCI’s UPI Help system was designed in part to let users check pending transaction status and raise complaints when transactions have not been processed or the beneficiary has not received the money.
If the status does not resolve, use the complaint mechanism rather than repeatedly making the same payment.
What If the Refund Doesn’t Arrive After T+1 or T+5?
Now the issue becomes more serious.
First confirm which RBI category applies.
Money transfer
Your account debited but beneficiary not credited:
T+1
Merchant payment
Your account debited but confirmation not received at merchant:
T+5.
If you’re beyond the applicable timeline:
- Check whether the reversal has actually reached your bank account.
- Check the current transaction status.
- Use the UPI app’s complaint mechanism.
- Contact your bank if necessary.
- Keep the complaint/reference number.
- Mention the RBI failed-transaction TAT framework if your case falls within it.
And remember the compensation provision:
₹100 per day beyond the applicable timeline.
What If My Bank Doesn’t Resolve the Complaint?
Keep your complaint records.
RBI’s framework also says that customers can approach the Reserve Bank – Integrated Ombudsman Scheme for grievances under the framework.
That does not mean you should jump immediately to the Ombudsman for every five-minute UPI delay.
Use the normal complaint process first and preserve the evidence.
If the regulated entity does not resolve the grievance through the applicable process, escalation options become relevant.
Be Careful: A Failed UPI Payment Is Also a Scam Opportunity
This deserves special attention.
Imagine you’ve just lost sight of ₹10,000.
You’re worried.
You Google:
“UPI refund customer care number.”
A scammer knows you’re desperate to get the money back.
Never share your:
UPI PIN
OTP
Debit-card PIN
or other sensitive banking credentials with someone claiming they need them to “process your refund.”
Also remember:
You do not need to enter your UPI PIN to receive money.
Use support channels inside your legitimate UPI app or the official channels of your bank.
NPCI provides official UPI consumer support and educational resources rather than requiring users to rely on random numbers found through search results.
Quick Answer: When Will I Get My UPI Refund?
Here’s the part worth remembering.
| What happened? | RBI auto-reversal timeline | Compensation after deadline |
|---|---|---|
| Account debited, beneficiary not credited — UPI fund transfer | T+1 day | ₹100/day |
| Account debited, merchant doesn’t receive transaction confirmation | T+5 days | ₹100/day |
These are the RBI framework timelines for the specified failed-transaction categories.
So when someone tells you:
“Every UPI refund takes one day.”
that’s too simplistic.
And:
“Every UPI refund takes five days.”
is also too simplistic.
The type of failed transaction matters.
What Should I Do Right Now?
If your UPI payment failed but money was debited:
1. Check the transaction status
Is it Failed, Pending, or Successful?
2. Check whether the receiver actually received the money
Don’t rely only on what one screen says.
3. Identify the transaction type
Was this a transfer to another person/account or a payment to a merchant?
4. Save the transaction ID and screenshots
Do this before anything changes.
5. Use your UPI app’s complaint/support function
NPCI’s UPI Help framework supports complaints for relevant debit transactions.
6. Know the applicable RBI timeline
T+1 for the specified failed fund transfer.
T+5 for the specified failed merchant payment.
7. Escalate if the problem remains unresolved
Keep all complaint/reference numbers.
8. Know your compensation rights
The RBI framework specifies ₹100 per day when reversal exceeds the applicable outer limit in these UPI categories.
So, Where Did My Money Go?
If your UPI transaction failed after your bank account was debited, the most important thing is not to assume:
“My money is gone forever.”
Instead ask:
Was this a failed transfer or a failed merchant payment?
That determines which timeline may apply.
For the failed UPI categories covered by RBI’s framework:
Transfer to beneficiary → T+1
Merchant payment → T+5
and delays beyond the applicable timeline carry a prescribed ₹100-per-day compensation.
Meanwhile, NPCI’s UPI Help guidance says that for a wrong debit in a pending/failed transaction, the money will be credited back and a concern can be raised through UPI Help.
So don’t just wait nervously while refreshing your bank balance.
Check the status.
Save the transaction ID.
Know whether T+1 or T+5 applies.
And if the money doesn’t return within the applicable period, raise and preserve a formal complaint.